
Growth Strategies, Insights & Trends
Omnichannel is the New Standard in Canadian Retail
Omnichannel retail works best when store, web and mobile payments share one system. Get insights for Canadian retail.
 Calculating time...
Most Canadian businesses will pay less when they understand which card types and payment channels set their processing costs, and recent federal agreements aimed to cut eligible small-business interchange fees by up to 27 per cent.
If you run a Canadian shop, restaurant, clinic or online store, fee quotes can look simple until the monthly statement arrives. A posted rate often blends card network costs, card type and the way the payment was accepted. That’s why plain language helps more than a long schedule of terms. Once you can separate percentage-based credit fees from flat debit charges, you can compare options using the sales mix you already have.
Most credit card processing fees in Canada land between about one and three per cent per sale, plus a small fixed amount in some plans. Your actual cost comes from the card used, the sales channel and the markup charged by your processor. That range is normal, not a sign that a statement is wrong.
A $40 café purchase on a basic card will usually cost less than the same $40 sale on a premium rewards card. An online order for the same amount will often cost more again because the fraud risk is higher and the checkout requires extra checks. Federal fee agreements still matter here because the average effective interchange rate for eligible small businesses was reduced to 0.95 per cent from 1.4 per cent. That tells you the headline rate matters, but the details behind the rate matter just as much.Interchange is the base fee built into most credit card transactions. It is paid to the card issuer and sits under the total amount you see on your merchant statement. Your processor adds its own charge on top, which is why two providers can quote different prices for the same sale type.
A $120 invoice paid in person gives a useful example. Part of the fee goes to the issuer through interchange, part covers network access and part is the processor’s margin for moving the payment through authorization and settlement. You do not negotiate interchange card by card, but you can compare how clearly a provider separates its own pricing from those pass-through costs. If the statement hides everything in vague categories, you will struggle to tell what you’re actually paying for.
Premium rewards cards usually cost more to accept than standard consumer cards because their interchange rates are higher. The extra rewards cardholders receive are partly funded through those higher merchant costs. If a large share of your customers use premium cards, your average credit fee will rise even if your sales volume stays the same.
A restaurant that sees a lot of business-travel spending often feels this first. Two dinner bills of $85 can produce different fees simply because one guest taps a standard card and another uses a premium travel card. You can’t control which card a customer presents, but you can review your monthly card mix and stop judging all credit volume as if it carries one uniform rate. That single check usually explains why a quoted “starting at” price never matches the full month.
Card-present payments usually cost less because the card, device and cardholder are all present at the time of purchase. That lowers fraud risk and makes authorization more straightforward. Online, phone and manually keyed transactions usually carry higher fees because extra verification steps are needed and the risk profile is different.
A customer who taps a card at your front counter creates a cleaner transaction than a customer who reads the card number over the phone. An online checkout with address checks and security prompts still counts as card-not-present, so it’s usually priced above an in-store tap sale. That difference matters most if you sell across more than one channel. If half your sales happen online and half happen in store, you should expect more than one effective rate in the same month.
Debit card processing fees in Canada are usually charged as a flat amount per transaction instead of a percentage of the sale. That means the fee often stays the same on a small purchase and a larger purchase, especially for card-present debit. It makes debit costs easier to estimate before the statement arrives.
A $6 coffee and a $60 haircut can carry the same debit fee even though the ticket size is very different. That structure helps small-ticket businesses because the fee doesn’t climb with the sale amount the way credit fees do. It also changes how you compare plans. If most of your volume comes through debit, you should pay close attention to the posted per-transaction amount rather than focusing only on the credit percentage in the ad.
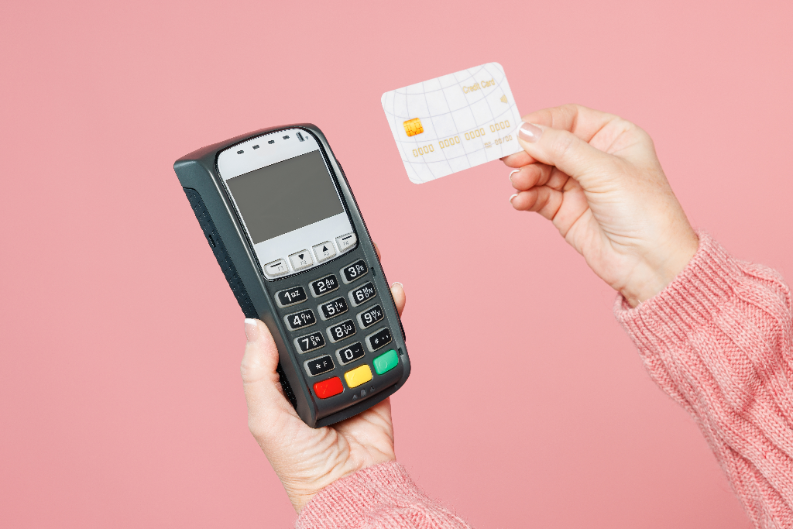
Interac Debit is usually less expensive than credit because it is commonly priced as a flat card-present transaction fee, while credit is usually priced as a percentage of the sale. That cost gap becomes more noticeable as your average ticket rises. It is one of the clearest fee differences on a Canadian statement. With Moneris, Interac Debit purchases come with a low, single flat processing fee and no chargebacks on all Interac Debit purchases, helping businesses keep payment costs more predictable. Learn more about Moneris Interac Debit processing solutions.
A $100 purchase shows the gap clearly. If debit costs a flat fee, the charge stays small and predictable. If credit costs around one to three per cent, the fee rises with the value of the sale. That is why retail, service and quick-service businesses often watch their debit mix closely when they review monthly payment costs.
|
Common payment setup |
What the fee usually looks like |
What you should watch on the statement |
|
Card-present debit on a small purchase |
The fee is often a flat amount that does not rise with the ticket value. |
Check the posted per-transaction charge and count how often debit is used. |
|
Card-present credit on a standard consumer card |
The fee is usually a percentage of the sale with a lower base than premium credit. |
Review your blended rate so standard credit is not mixed up with rewards-heavy volume. |
|
Card-present credit on a premium rewards card |
The fee usually runs higher because the card category carries higher interchange. |
Look for card-mix reporting that shows how much premium volume you actually take. |
|
Online or manually keyed credit payment |
The fee often rises because card-not-present transactions have extra risk checks. |
Separate online from in-store volume before you compare providers or plans. |
|
Higher average ticket sizes |
Flat debit pricing tends to stay steady while percentage-based credit fees rise with the sale. |
Use your average ticket to estimate cost, not just the advertised starting rate. |
A published price sheet gives you the clearest answer to what each transaction costs because it shows the fee structure before you sign up. Moneris lists flat-rate pricing publicly, including a current example of card-present Interac Debit at $0.12 per transaction on our pricing page. Credit rates should be checked on that page by channel because online and in-store pricing are not always the same.
That kind of posted pricing helps you ask better questions. You can match the fee to the way you sell, check if the rate applies only to card-present payments and confirm if monthly account charges sit outside the transaction price. A contractor who sends invoices online should not rely on a card-present debit number to judge total payment cost. Clear pricing does not remove every variable, but it does remove the guesswork that pushes people to comparison sites.
The right pricing model matches your average sale size, your debit share and the channels where customers pay you. A low percentage can look attractive until fixed fees add up on small tickets. A flat debit fee can look minor until you compare it against hundreds of monthly transactions. Good comparison starts with your own sales pattern.
A coffee shop with frequent low-value payments should read pricing differently from a home services business with fewer, larger invoices. That is why last month’s transaction report is more useful than a generic calculator. If most orders happen in person, card-present debit and standard credit rates deserve the closest look. If online checkout carries a big share of your volume, you should weigh those fees on their own instead of folding them into one blended number.
That habit gives you a clearer view than any headline rate. You’re no longer guessing which costs come from card choice and which come from your provider’s markup. Using Moneris published pricing as a reference point can help you test your own transaction mix against a clear public schedule. Clear fees will not make every business cheaper to process, but they do make your choice easier to justify.
Growth Strategies, Insights & Trends
Omnichannel retail works best when store, web and mobile payments share one system. Get insights for Canadian retail.

Growth Strategies, Small Business
More than half of Canadians now use AI to shop. See how AI is reshaping online shopping and what your Canadian small business can do to show up, build trust and win.
Ecommerce, Moneris Online, Growth Strategies
Get insight into Tap to Pay on iPhone in Canada, including Interac Debit support, setup and small-business sales use.
Growth Strategies, Small Business
Learn how to optimize your social media strategy with practical tips on content, captions, advertising, metrics and platform selection. Discover how Canadian small businesses can turn social media into a growth channel.