
Growth Strategies
Omnichannel is the new standard in Canadian retail
Omnichannel retail works best when store, web and mobile payments share one system. Get insights for Canadian retail.
 Calculating time...
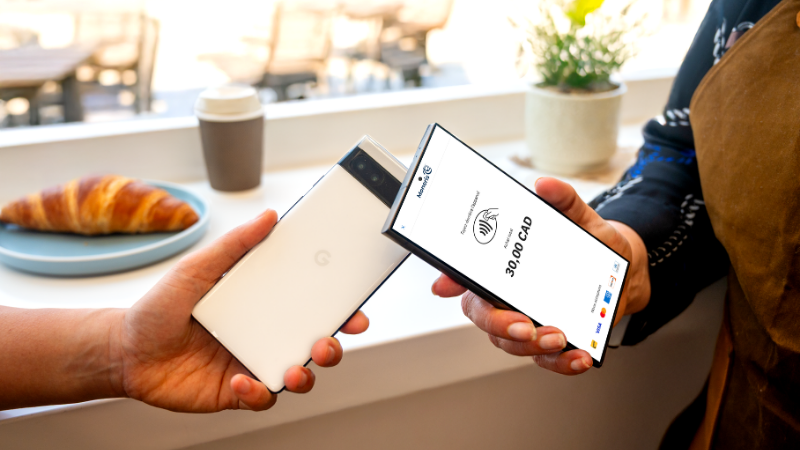
Every payment transaction in Canada relies on an interconnected ecosystem of businesses, financial institutions, payment networks and technology providers working together to move funds securely. A transaction completes in seconds, but multiple participants help initiate, authorize, process and settle the payment. Understanding who those participants are, the role each plays and how they work together provides important context for payment processing, data residency, infrastructure and ownership. Modern payments depend on a combination of Canadian and global participants, and no provider operates in isolation. What distinguishes providers is the role they play within the ecosystem, how they support customers, where they operate and the infrastructure, governance and controls behind their services.
When a customer taps, inserts or clicks to pay, it feels instant. In the seconds that follow, a network of technology providers, financial institutions and payment partners work together to move money securely from your customer's account, through multiple systems and organizations and into your business account.
Whether the sale happens in-store, online or on the go, every electronic payment transaction moves through six steps. Each involves organizations with a distinct role to authorize, process and settle the transaction:
Most businesses and consumers never see these steps because the whole exchange takes seconds. The experience looks simple, but a network of organizations must communicate to verify the transaction, protect information, manage risk, confirm funds are available and deliver those funds securely so your business gets paid. Understanding this process gives you important context when you evaluate payment providers.
Every payment transaction relies on a network of participants, each responsible for a specific role in moving money securely and efficiently through the ecosystem. Here are the key participants in a typical transaction:
Cardholder: your customer. The individual or business making the purchase and the account the funds come from
Merchant: your business, or any business selling goods and services and accepting customer payments
Issuer: the financial institution behind the customer's payment card. The issuer extends the credit and approves or declines each transaction
Payment network: the organization, such as Visa, Mastercard, American Express and Interac, providing the infrastructure, standards and operating rules to move transactions between participants
Merchant acquirer or payment processor: the organization holding the merchant's card acceptance relationship, processing transactions and facilitating settlement. Some providers rely on third parties and act mainly as distributors of payment services. Moneris serves as both acquirer and processor, giving merchants a direct processing relationship and end-to-end accountability for payment acceptance and settlement
At Moneris, our focus stays on helping your business accept payments, serve customers and grow with confidence. Moneris is the leading payments and commerce solutions provider in Canada. Founded in 2000 by the Royal Bank of Canada (RBC) and the Bank of Montreal (BMO) and headquartered in Toronto, Moneris operates a Canada-resident technology infrastructure and provides payment processing payments services through Canadian employees, Canadian leadership and Canadian operations.
In August 2026, we announced an agreement for Francisco Partners, a global technology investment firm, to acquire Moneris, subject to regulatory approvals and closing conditions. Moneris' 2,000 Canadian employees, Canadian leadership team, Canadian offices, Canada-resident technology infrastructure and long-term referral relationships with RBC and BMO continue.
This differs from providers operating as independent sales organizations or payment facilitators. Those providers market and sell payment solutions but rely on a larger organization for the acquiring relationship and the movement of money. Knowing who provides your processing services and where that infrastructure resides helps you evaluate service, support, risk management and overall fit. If you are comparing providers, these questions are a good place to start:
Every day, our teams work with businesses of all sizes, from entrepreneurs and small businesses to some of Canada's largest organizations, helping them operate in a complex commerce environment. Payments happen in seconds, but the systems, people, expertise and infrastructure behind them represent a significant, ongoing investment in helping Canadian businesses succeed.
Modern payments are interconnected by design. A single tap in Canada can involve a Canadian business, their acquirer and processor, a Canadian financial institution, a global payment network, a mobile wallet provider and multiple technology platforms, all working together in seconds.
This is one of the most important aspects of the payments ecosystem: no payment provider operates in isolation.
Different participants play different roles. As a result, the payments ecosystem is built on a combination of Canadian, U.S. and international participants. This is not unique to any one provider. If your business accepts electronic payments in Canada, you already rely on a mix of domestic and global infrastructure to facilitate transactions, protect information and support the movement of money.
This context matters for businesses working to understand how modern payments operate. Payment transactions processed in Canada, including those through Moneris and other providers, rely on global payment networks and interconnected technology ecosystems. That interconnectedness has existed for decades and is a fundamental characteristic of modern commerce.
What differs from provider to provider is the role they play, who holds the merchant relationship, where support is delivered, how funds are settled and managed and the technology, security and operational controls behind the service.
If you're evaluating payment providers, understanding those distinctions is more valuable than focusing on any single component of the payment journey. Modern commerce depends on an ecosystem of participants working together, and understanding how they interact gives you a clearer picture of how payments really work.
Questions about data residency, payment routing and payment infrastructure have become more common as businesses evaluate payment providers and work to understand how electronic payments function.
These concepts are often discussed together, but they refer to different aspects of the payments ecosystem.
Data residency refers to where information is stored and managed. Depending on the provider and the type of information involved, data may be stored within Canada, in other jurisdictions or across multiple locations as part of a broader technology infrastructure.
When evaluating a provider, you should understand where their systems operate, how information is protected, what security controls are in place and how the provider complies with applicable regulatory and contractual requirements.
Payment routing is distinct from data residency. A transaction may route through multiple participants and networks domestically and internationally during authorization and settlement, while data storage, operations and support are managed in different locations depending on the provider's operating model.
Why do global payment networks matter?
Modern electronic payments are interconnected by design. Global networks give cardholders confidence, so no matter where they travel, they can use their preferred payment type without issue. When a Canadian business accepts a credit or debit card issued domestically or internationally, the transaction typically relies on payment networks such as Visa, Mastercard, American Express or Interac, along with the financial institutions and technology providers behind those networks.
This interconnection is a fundamental characteristic of modern payments and has been for decades. Every participant relies on a combination of infrastructure, standards, technology and operational processes to move transactions securely between merchants, financial institutions and payment networks.
When assessing payment providers, consider a range of factors, including:
Understanding these distinctions gives you a more complete picture of how a provider supports payment acceptance and merchant operations than focusing on any single component.
Payment discussions often focus on a single company, technology platform or aspect of the transaction. In reality, the payments ecosystem is built on a broad network of interconnected participants working together to support commerce.
The infrastructure behind modern payments includes payment processors, financial institutions, payment networks, technology providers, cybersecurity controls, operational teams, customer support organizations and regulatory frameworks. No single organization operates in isolation.
This model is not new. Canadian businesses accepting electronic payments have long relied on a combination of Canadian, U.S. and international participants to facilitate transactions, protect information and move money securely throughout the economy.
Understanding these relationships helps you evaluate providers, assess risk and appreciate the many participants working together behind every transaction.
Modern payments are built on collaboration.
Financial institutions, payment networks, technology partners and operational processes, spanning Canadian, U.S. and international companies, all work together to move money safely and efficiently throughout the Canadian economy.
Consumers and merchants experience the transaction in seconds, but the system behind it reflects the scale, sophistication and interconnected nature of today's commerce ecosystem.
Understanding how these participants work together helps your business make more informed decisions about the providers, partners and solutions you choose.
At Moneris, we believe businesses make better decisions when they understand how the systems behind their payments work. By helping Canadian merchants understand the technology, relationships and infrastructure behind every transaction, we aim to provide greater clarity into the interconnected ecosystem that powers Canadian commerce.
Growth Strategies
Omnichannel retail works best when store, web and mobile payments share one system. Get insights for Canadian retail.
Growth Strategies
Get practical marketing ideas for restaurants, retailers, and ecommerce to win the Halloween season in Canada.

Growth Strategies, Small Business
More than half of Canadians now use AI to shop. See how AI is reshaping online shopping and what your Canadian small business can do to show up, build trust and win.
Ecommerce, Moneris Online, Growth Strategies
Get insight into Tap to Pay on iPhone in Canada, including Interac Debit support, setup and small-business sales use.